34%
of an average insurer's operating cost sits in underwriting, claims handling and policy servicing, the three processes automation reaches first.
McKinsey, Insurance Productivity Benchmark
AI for Insurance
We build the systems that decide faster and pay sooner: straight-through underwriting, automated claims triage, fraud scoring that survives a regulator's question and policy administration that does not depend on a spreadsheet. Every model ships with the rationale attached, because in insurance an unexplainable decision is not a decision.
Axiomra is a custom insurance software development company working with carriers, MGAs, brokers and insurtechs on the parts of the business that decide margin: how a risk is priced, how a claim is triaged and how much of either still needs a human. We design and build the platforms that carry those decisions end to end, on top of the policy administration system you already run.
Our AI insurance software development services pair document intelligence, behavioural fraud models and portfolio analytics with the governance layer a supervisor will ask for: feature lineage, challenger models, bias testing and a written reason for every automated outcome. The result is a book you can price with confidence and a claims queue your adjusters can actually clear.
Insurance was always a data business; what changed is that the data now arrives faster than a manual process can read it. Telematics, imagery, medical records and open claims feeds only pay back when something can act on them in the moment, which is what AI insurance software development services are actually for.
34%
of an average insurer's operating cost sits in underwriting, claims handling and policy servicing, the three processes automation reaches first.
McKinsey, Insurance Productivity Benchmark
84%
of carriers name claims automation and fraud analytics as their highest-priority AI investments for the next two years.
Deloitte, Global Insurance Outlook
7%
of gross written premium is lost to claims leakage and undetected fraud across a typical general insurance book.
Insurance Europe, Fraud & Leakage Estimates
What we actually promise
Every automated decision arrives with its reason attached.
Every model is tested for drift and for bias before it prices a risk.
Every claim your team still touches is one the machine could not justify closing alone.
That is the whole contract. Everything below is how we build it.
Overcoming key barriers in insurance operations
First notice of loss arrives as a phone call, a form and a folder of photographs, and then waits for an adjuster with capacity. We build intake that reads the documents and imagery on arrival, scores severity and complexity, settles the clean low-value claims straight through and routes the rest to the adjuster whose caseload and licence actually fit. The queue stops being first-in-first-out and starts being worst-first.
What insurance solutions do we offer?
We build across the whole policy lifecycle rather than dropping a model into one step of it. Each stage below is a system we have shipped: integrated with the core, governed from day one and measured on the number it was meant to move.
Embedded and direct quote journeys that price in real time, pre-fill from third-party data and bind without a callback. Broker and aggregator channels run off the same rating service, so a rate change lands everywhere at once.
Quote-to-bind in one session
Submission ingestion that reads broker packs, schedules and loss runs, enriches them with exposure data and applies appetite automatically. Underwriters open a triaged risk, not a mailbox.
Straight-through on clean risks
Configuration-driven products, endorsements and renewals sitting over your system of record, with an event layer that keeps every downstream service (billing, documents, reporting) in step without a nightly batch.
New product without a core release
Loss notification through any channel, with document and image understanding on arrival. Severity, complexity and coverage questions are scored before a human opens the file, and low-complexity claims settle straight through.
Worst-first, not first-in-first-out
Computer vision on claim imagery producing a first estimate and a repair-versus-total call, benchmarked against your own historical settlements rather than a vendor's national average.
Consistent estimates across adjusters
Network analytics across claimants, repairers, providers and devices, with behavioural scoring at intake and at payment. Investigators get ranked referrals with the evidence assembled, not a list of rule hits.
Higher SIU hit rate, shorter queue
Automatic identification of recovery potential at first notice, document assembly for demand packs, and litigation-risk scoring so reserves and settlement authority reflect the actual exposure.
Recovery spotted at FNOL, not at close
Assistants grounded in the policy wording and live claim state, plus renewal and lapse models that tell the retention team which policyholder is worth a call this week.
Fewer status calls, better renewals
Ready to level up?
Bring us the process that costs you the most, whether that is the claims backlog, the referral queue or the submission mailbox, and we will scope what automation realistically moves, and what it will not. No pilot theatre.
Get in touchWhat kinds of insurance systems do we build?
End-to-end delivery, from the first workshop to the model monitoring dashboard your risk function signs off on. We work alongside your underwriting, claims, actuarial and compliance teams rather than around them.
We map the policy lifecycle against where your cost and leakage actually sit, then rank the automation candidates by return rather than by how demonstrable they are. Expect us to name the processes that are not worth automating yet, usually the ones with the prettiest demos.
Underwriting workbenches, claims platforms, broker portals and embedded distribution built to sit alongside Guidewire, Duck Creek, Sapiens or a legacy core you are not replacing this year. Event-driven, idempotent integrations, delivered in increments you can put in front of a regulator.
Governed data on top of policy, claims and third-party feeds, with loss-ratio monitoring, reserve analytics and segment drift detection. One set of figures that underwriting, actuarial and finance all read from, so the pricing conversation stops being a reconciliation.
Document understanding across submissions, medical records, loss runs and claim evidence, wired into workflows with human-in-the-loop checkpoints where the stakes justify one. Every automated step writes its own audit trail.
Whom do we build insurance software for?
Submission workbenches, delegated authority reporting and bordereaux automation, so binder compliance stops being a month-end spreadsheet exercise.
Triaged submissions, appetite rules in one place and portfolio exposure visible before the quarter closes rather than after it.
Severity-ranked queues, straight-through settlement on clean claims and referrals that arrive with the evidence already assembled.
Governed experience data, challenger models and the ability to test a rate change against the live book before it is filed.
A ledger built to the rules your regulator applies, a rating service and the reporting asked for on day one, built to survive the first capacity partner's due diligence.
One view of combined ratio, reserve adequacy and automation coverage that holds up in a board pack, refreshed continuously instead of assembled overnight.
Which lines of business do we serve?
Every line carries its own regulator, its own data and its own definition of an acceptable loss. Hover any card to see what we build for it.
Telematics-based pricing, photo-first FNOL and repair-versus-total calls benchmarked on your own settlement history.
Perils modelling on live geospatial data, automated inspection triage and catastrophe surge planning that holds when the queue triples overnight.
Accelerated underwriting on medical evidence, mortality experience analytics and orphan-policy servicing that stops a book going quiet.
Claims adjudication against policy wording, provider network analytics and pre-authorisation that answers while the patient is still in the room.
Submission ingestion across broker packs, exposure aggregation by location and appetite rules applied before an underwriter opens the file.
Real-time disruption feeds, automated eligibility checks and settlement for low-value claims before the policyholder has landed.
Attack-surface scoring at quote, exposure accumulation across a portfolio and incident-cost modelling on live threat intelligence.
Voyage and route risk scoring, shipment-level exposure tracking and claims evidence assembled from carrier and IoT telemetry.
What changes once it is live?
Triage at intake and straight-through settlement on clean claims take the waiting out of the majority of files, so adjuster capacity goes to the ones that genuinely need judgement.
Behavioural and network scoring catches the schemes a rule set was never written for, and evidence assembly means referrals arrive ready to investigate rather than ready to triage again.
Enriched submissions and continuously monitored experience data let underwriters see segment drift while it is still small, instead of meeting it in next year's loss ratio.
Configuration over code, and an integration layer that isolates the core, means a new cover or channel is a product decision rather than a vendor release slot.
Decision reasons, feature lineage, bias testing and challenger comparisons are part of the build, so an automated outcome can be explained to a policyholder, an ombudsman or a supervisor.
Assistants grounded in the policy wording and the live claim record answer status questions immediately and escalate cleanly the moment a question becomes advice.
Where to start
One session, your process map, and an honest read on what automation moves and what it does not. We will leave you with a sequenced plan whether or not you build it with us.
Bring the parts that hurt: the claims your adjusters argue about, the submissions that sit unread for a week, the renewals priced on instinct. We trace where the data already lives, where it is missing, and which decisions a model should be allowed near.
No slide deck at the end of it. A sequenced plan, a cost range, and a plain list of the things we would leave to your people.
What innovations have we delivered to businesses?
Work delivered for insurers, MGAs and brokers, with the number each build had to move.
Virtual Sales & Customer Support Assistant
Patient Intake & Triage AI Agent
Healthcare Chatbot & Virtual Assistant
AI Financial Advisor Assistant
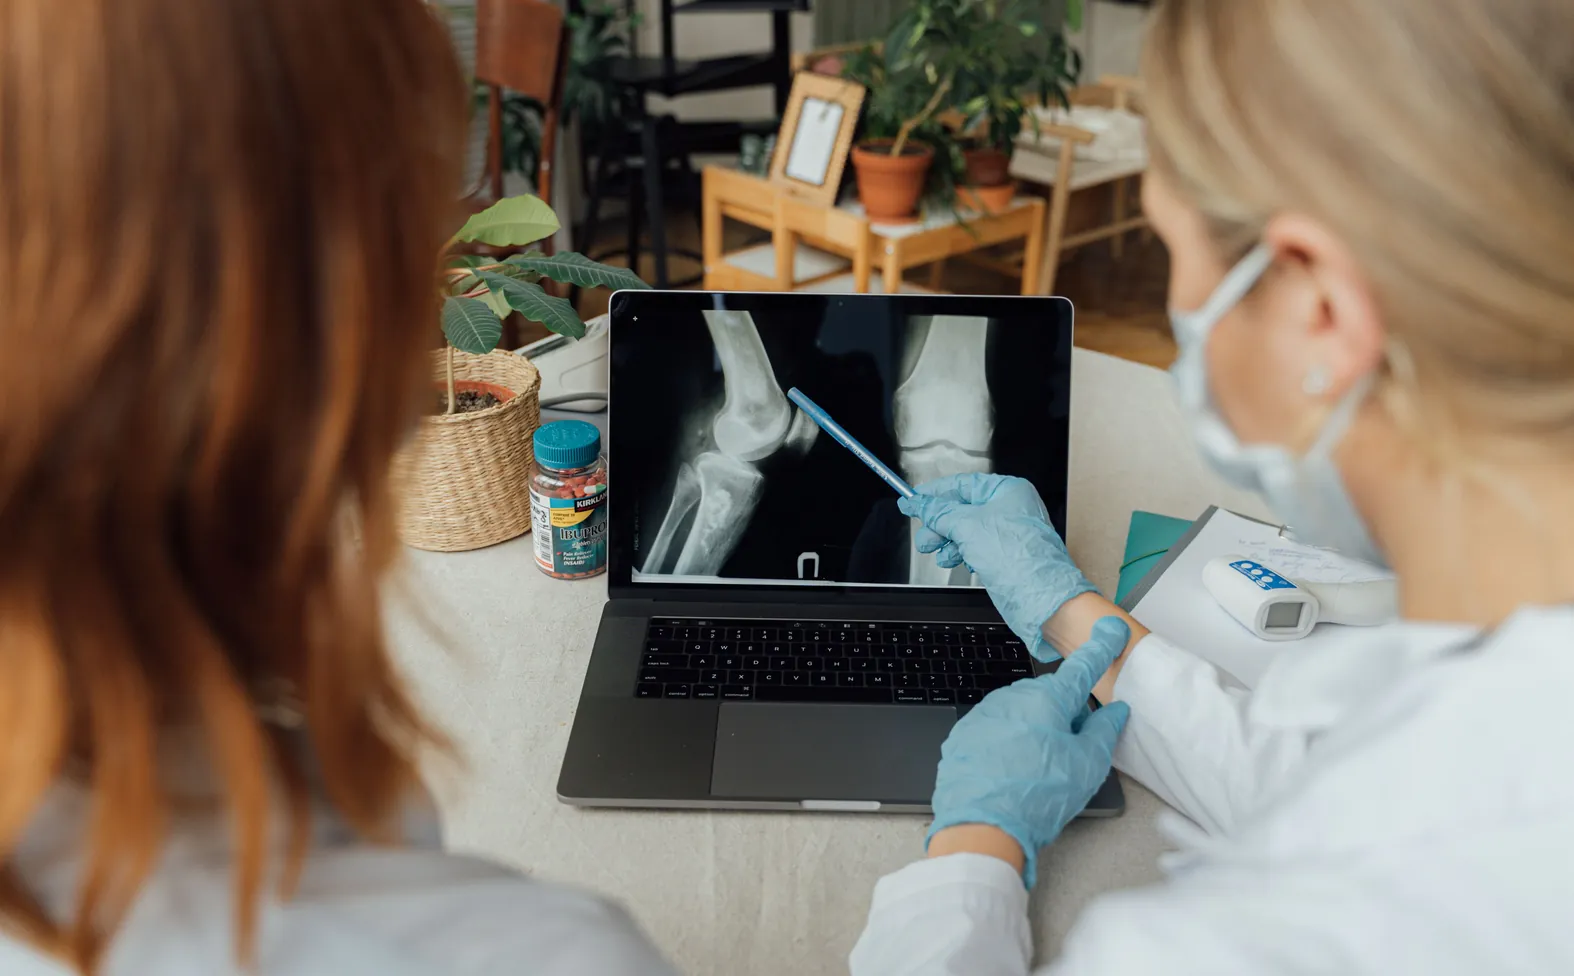
Medical Imaging & Disease Identification
AI Physical Therapy Coach
Readmission Risk Prediction
Regulatory Document Analysis
Customer ID Checks & Onboarding Automation
In-Store AI Shopping Assistant
AI Fraud Detection for Payments
AI-Powered Personalized Marketing
AI Credit Scoring for Lenders
AI Inventory & Demand Forecasting
Smart Pricing for Retail
Technologies we work with
The same production-grade toolchain sits under every insurance platform we ship. Pick a layer to see what it is made of.
Who do we work with?
We help founders get a licensed product live: a rating service, a ledger built to the rules your regulator applies, a claims flow that scales past the first surge, and the reporting a capacity partner will ask for during due diligence.
Delegated authority runs on evidence. We automate bordereaux, binder compliance and submission handling so the carrier relationship is governed by data rather than by a monthly spreadsheet exchange.
Enterprise obligations, a fraction of the enterprise headcount. Our automation and analytics tooling closes that gap without a core replacement programme or a three-year rollout.
We partner on governed data layers, core integration and AI systems that clear security, model risk and procurement before they ever reach production, and keep clearing them afterwards.
Why is it worth working with us?
“Commendable work by the team. They collaborated and communicated in a highly professional manner and delivered exactly what was asked in the desired time frame. Their project management and communication skills are highly appreciable.”
Why choose Axiomra?
Every system is scoped against a number it has to move: cycle time, leakage, loss ratio, straight-through rate. If a piece of work cannot name its number, we will tell you rather than build it.
Guidewire, Duck Creek, Sapiens or a legacy core nobody wants to touch: we integrate through an event layer that isolates the system of record, so new products ship without a core release.
Decision reasons, feature lineage, bias testing and challenger models are delivered with the model, not retrofitted when a supervisor asks. Plus 60 days of technical support and team training after go-live.
500+
Projects Delivered
170+
Valuable Partnerships
30+
Countries Served
85+
Tech Experts
Recognised & certified
Insurance questions
By deciding what a claim is before a human opens it. Document and image understanding at first notice produce a severity and complexity score, clean low-value claims settle straight through, and everything else is routed to the adjuster whose caseload and licence fit. The saving is mostly queueing time, not handling time.
Talk to our engineers about claims automation, underwriting intelligence or the governance layer underneath both. No sales desk in the middle.
Get your project done!